


What factors affect solar project insurability?
Solar project insurability depends on a complex web of technical, financial, and regulatory factors that insurers carefully evaluate before providing coverage. Understanding these factors is crucial for project developers, investors, and stakeholders who need comprehensive insurance protection for their renewable energy investments.
The insurance landscape for solar projects has evolved significantly as the industry has matured, with insurers developing more sophisticated risk-assessment frameworks. These evaluations can make the difference between securing affordable coverage and facing limited options or prohibitive premiums.
What makes a solar project insurable in the first place?
A solar project becomes insurable when it demonstrates acceptable risk levels across technical design, financial viability, regulatory compliance, and operational management. Insurers require evidence that the project follows industry best practices and maintains professional oversight throughout its life cycle.
The foundation of solar project insurability rests on several core elements. First, the project must use certified components from reputable manufacturers with established warranty programs. This includes solar panels that meet international standards, inverters from recognized suppliers, and mounting systems designed for local conditions.
Professional involvement is equally critical. Insurers expect qualified engineering firms to design the system, certified installers to handle construction, and experienced operators to manage ongoing maintenance. The presence of these professional stakeholders significantly reduces technical and operational risks.
Financial transparency also plays a vital role. Projects with clear funding structures, realistic financial projections, and adequate contingency reserves demonstrate lower default risk. Insurers prefer projects backed by creditworthy entities or those with power purchase agreements from reliable offtakers.
Which technical factors do insurers evaluate most heavily?
Insurers focus most heavily on component quality, system design adequacy, installation standards, and ongoing maintenance protocols. These technical factors directly correlate with claim frequency and severity, making them primary drivers of insurance decisions and pricing.
Component selection carries significant weight in insurer evaluations. Solar panels must come from Tier 1 manufacturers with strong financial backing and comprehensive warranty programs. Inverter selection is equally scrutinized, with preference given to proven technologies from established suppliers. Mounting and racking systems must demonstrate appropriate engineering for local wind and snow loads.
System design receives thorough review for electrical safety, structural integrity, and performance optimization. Proper grounding, arc-fault protection, and DC isolation switches are essential safety features. The electrical design must comply with relevant codes and standards, with clear documentation of load calculations and safety margins.
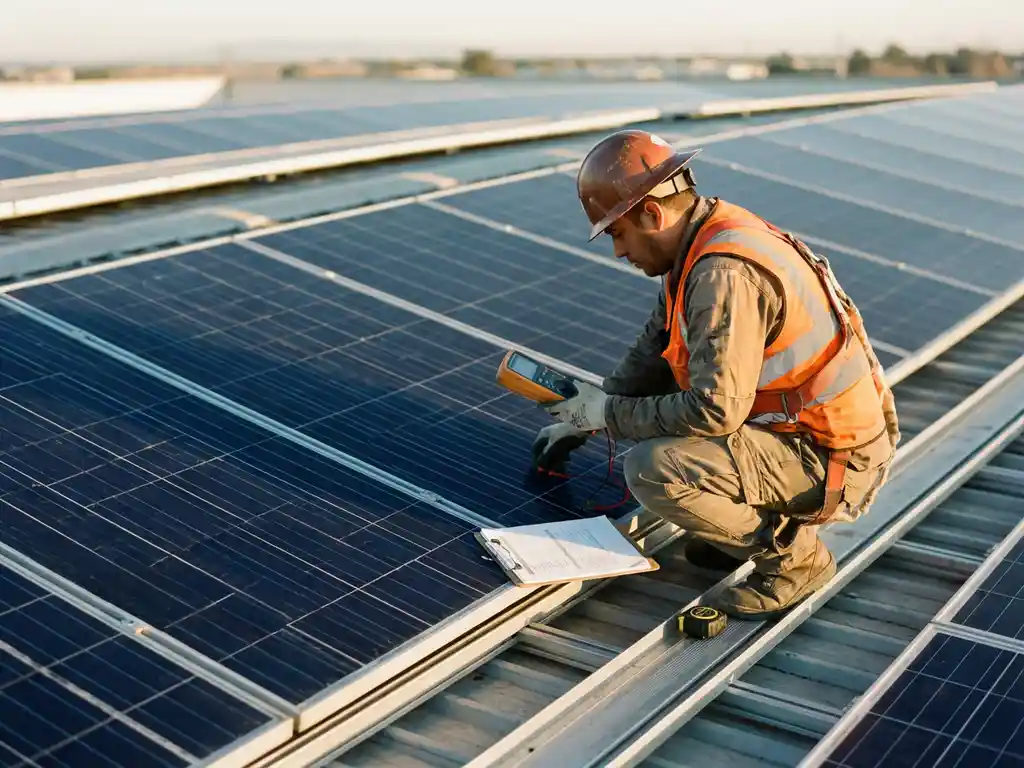
Installation quality significantly impacts long-term performance and safety. Insurers often require installation by certified professionals following manufacturer specifications. Proper cable management, weatherproofing, and structural attachments are critical elements that insurers evaluate through inspection reports.
Quality assurance processes, including commissioning tests and ongoing monitoring systems, demonstrate proactive risk management. Projects with comprehensive testing protocols and real-time performance monitoring typically receive more favorable insurance terms.
How do financial structures affect insurance availability?
Financial structures directly impact insurance availability by influencing credit risk, project viability, and the insurer’s ability to recover claims payments. Strong financial backing and transparent ownership structures enhance insurability, while complex or undercapitalized arrangements may limit coverage options.
Project ownership structure plays a crucial role in insurance decisions. Corporate-owned projects with strong balance sheets typically secure coverage more easily than complex partnership arrangements or special-purpose vehicles with limited assets. Insurers prefer clear ownership chains and avoid structures that could complicate claims resolution.
Debt financing arrangements affect insurance requirements and availability. Lender requirements often drive insurance specifications, with project finance deals typically demanding comprehensive coverage packages. The presence of experienced lenders can actually improve insurability by ensuring professional project oversight and risk management.
Power purchase agreements significantly influence insurance decisions. Long-term contracts with creditworthy offtakers provide revenue certainty that reduces project risk. Conversely, merchant projects or those dependent on volatile market pricing may face higher premiums or coverage limitations.
Contingency reserves and financial buffers demonstrate responsible project planning. Insurers favor projects with adequate reserves for unexpected costs, maintenance requirements, and performance shortfalls. These financial cushions reduce the likelihood of insurance claims and project defaults.
What regulatory and compliance issues impact coverage decisions?
Regulatory compliance issues significantly impact coverage decisions by affecting project legality, operational permissions, and potential liability exposures. Noncompliance with building codes, environmental regulations, or grid interconnection requirements can make projects uninsurable or dramatically increase premiums.
Building and electrical code compliance forms the foundation of regulatory requirements. Projects must obtain proper permits and pass required inspections to demonstrate adherence to safety standards. In the Netherlands, while Scope 12 inspections are not legally required for solar installations, most insurers demand them before providing coverage for commercial projects.
Environmental compliance encompasses various regulations depending on project location and size. Larger installations may require environmental impact assessments, wildlife protection measures, or habitat restoration plans. Failure to address these requirements can create significant liability exposures that insurers must consider.
Grid interconnection approvals are essential for utility-connected projects. Proper interconnection studies, protection schemes, and utility agreements demonstrate that the project can operate safely within the electrical grid. Projects without proper grid approvals face operational and liability risks that concern insurers.
Ongoing regulatory obligations continue throughout project operation. This includes compliance with performance standards, safety regulations, and reporting requirements. Projects with robust compliance management systems demonstrate lower regulatory risk and typically receive more favorable insurance terms.
How do location and environmental risks influence insurability?
Location and environmental risks significantly influence insurability by determining exposure to natural disasters, climate conditions, and geographical hazards. Insurers use sophisticated modeling to assess these risks, with high-risk locations facing higher premiums or coverage restrictions.
Natural disaster exposure varies dramatically by location and directly impacts insurance pricing. Projects in hurricane-prone coastal areas, earthquake zones, or hail-prone regions face elevated physical damage risks. Insurers use catastrophe modeling to quantify these exposures and price coverage accordingly.
Climate conditions affect both performance and durability risks. Extreme temperatures, high humidity, salt air, and UV exposure can accelerate component degradation and increase maintenance requirements. Desert installations face dust accumulation challenges, while coastal projects face corrosion risks from salt exposure.
Topographical factors influence both construction and operational risks. Steep terrain increases installation complexity and ongoing access challenges. Flood-prone areas require elevated mounting or flood-resistant designs. Projects in remote locations may face higher costs for maintenance and emergency response.
Local infrastructure and emergency services availability affects risk profiles. Projects near high-quality medical facilities and fire departments have better emergency response capabilities. Adequate road access ensures timely maintenance and reduces operational risks that concern insurers.
What documentation do insurers require for coverage approval?
Insurers require comprehensive documentation, including technical specifications, financial statements, permits, contracts, and risk assessments, to evaluate coverage applications. This documentation package must demonstrate project viability, regulatory compliance, and appropriate risk management across all project phases.
Technical documentation forms the core of insurance applications. This includes detailed engineering drawings, component specifications, installation procedures, and commissioning reports. Insurers need evidence that the system design meets industry standards and local requirements.
Financial documentation must demonstrate project viability and stakeholder creditworthiness. Required documents typically include audited financial statements, project pro formas, funding commitments, and power purchase agreements. Insurers analyze this information to assess default risk and coverage sustainability.
Regulatory documentation proves compliance with applicable laws and regulations. This includes building permits, environmental approvals, utility interconnection agreements, and inspection reports. For commercial projects, Scope 12 inspection reports are typically required by insurers even though they are not legally mandated.
Contractual documentation outlines project relationships and risk allocations. Key contracts include construction agreements, operations and maintenance contracts, equipment warranties, and professional services agreements. Insurers review these documents to understand risk distribution among project stakeholders.
Risk management documentation demonstrates proactive hazard identification and mitigation. This includes safety protocols, emergency response plans, monitoring systems, and maintenance schedules. Projects with comprehensive risk management programs typically receive more favorable insurance terms.
How Solarif helps with solar project insurability
We specialize in helping solar project developers and investors navigate the complex landscape of insurance requirements and risk assessment. With more than 15 years of experience and 521 Scope 12 inspections completed, we understand exactly what insurers look for when evaluating project insurability.
Our comprehensive approach to improving project insurability includes:
- Pre-project risk assessments to identify potential insurability issues early in development
- Scope 12 inspections by SCIOS-certified inspectors to meet insurer requirements for commercial installations
- Solarif-certified panel programs that provide enhanced warranty coverage and improved insurability
- Documentation review and preparation to ensure complete, accurate insurance applications
- Access to our international network of A-rated insurers through our Uniba Partners membership
Ready to ensure your solar project meets all insurability requirements and secures optimal coverage? Contact our renewable energy insurance experts today for a comprehensive project evaluation and a customized insurance solution.
Insurance and inspection needs for your BESS?
Contact us today if you want to know more about the possibilities in BESS insurance and Scope inspections.
📧 Email: support@solarif.com
☎️ Phone: +31 (0)26 711 5050